


TL;DR
- New markets and categories are attracting investment: Smadex reported sharp increases in spending in Nigeria, Ghana and Germany, while gaming led overall and education, health, music, magazines and dating gained ground.
- Let customers experience the proposition: Playable advertisements, interactive catalogues and conversational discovery can connect acquisition with a clearer understanding of what a subscription offers.
- AI, payments and localisation are changing the product: Faster adaptation, personalised experiences and familiar payment methods offer opportunities to build more valuable services, with growth depending on local commercial conditions.
|Watch the full session here |
The question “what’s hot in mobile content around the world?” sounds as though it should produce a list of countries and categories. At Telemedia Marbella, it led to a more fundamental discussion about what the industry is selling, how customers discover it and why they might keep paying.
Gaming remains a major acquisition category. Video is becoming more important to some providers, while education and services offering practical value are attracting attention. But the panel’s wider argument was that a catalogue of content is increasingly only the starting point. Customers expect a service that fits their interests, works across their devices and accepts the way they want to pay.
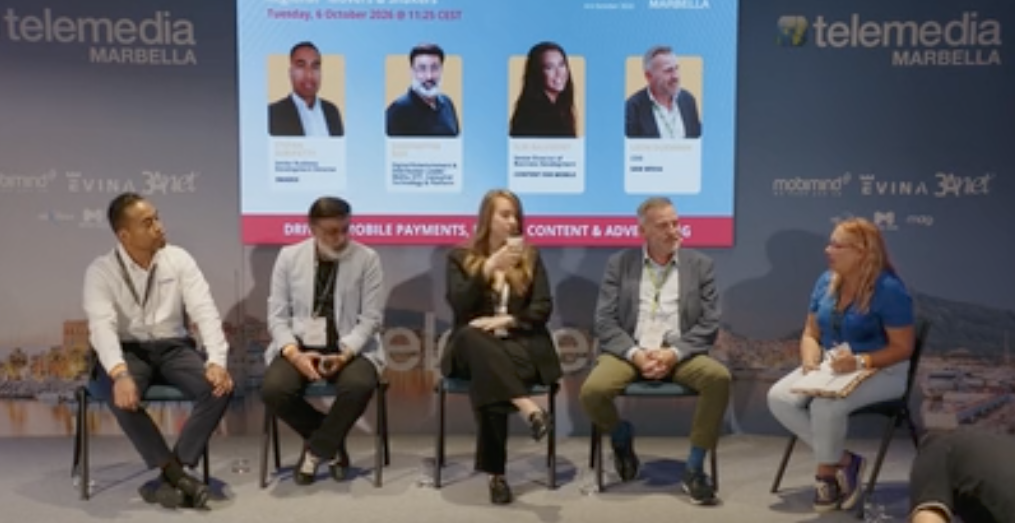
Chaired by Louise Ford, “What’s Hot in Mobile Content: Regional Movers & Shakers” brought together Stefan Suripatty, Senior business development director at Smadex; Ilse Balfort, senior director of business development at Content for Mobile; Leon Dijksman, COO of Sam Media; and Siddarthur Roy, former head of Hungama.
Suripatty opened with acquisition data showing how quickly opportunities can develop. Comparing October 2025 with September 2026, Smadex had seen advertising spend on its platform rise by more than 1,800% in Nigeria, around 300% in Ghana and 100% in Germany.
While these figures measure spending through Smadex, rather than the size or growth of the countries’ entire mobile content markets, they nevertheless show advertisers putting substantially more money into those territories.
Suripatty associated the growth with markets becoming easier to operate in and closer cooperation between aggregators, merchants and operators. Roy added that, in his assessment, greater currency stability and improved arrangements for paying merchants were helping Nigeria become more workable.
The distinction matters. An attractive consumer market does not necessarily become an investable one until the commercial infrastructure allows providers to collect and receive their revenue.
An audience question returned to precisely that issue: was Nigerian growth coming from local businesses or international entrants? Suripatty said both were involved, with local merchants defending their position as overseas players entered.
It echoed the Africa session’s message that market opportunity needs to be examined alongside payment, distribution and settlement. Population and demand are only part of the calculation.
So what is the hot content?
Across categories, gaming remained the largest vertical by advertising expenditure on Smadex. Suripatty also highlighted increasing spend in magazine content, health, music, education and dating.
Advertiser investment indicates activity, although it does not establish consumer demand or profitability. The direction was nonetheless interesting: the market is broadening beyond its most established acquisition categories.
Ilse Balfort described a similar shift within CFM’s operator discussions. Gaming remained in the portfolio and esports continued to attract interest, but video services were becoming more prominent in expansion conversations.
She associated that change with saturation in gaming and consumers’ growing familiarity with video-led experiences. Roy argued that short, vertical and snackable formats would become increasingly important, particularly for younger audiences.
That does not establish a universal category winner. Gaming’s scale, video’s momentum and education’s potential can coexist, with their prospects varying by market and proposition. Asked where he would place his next bet, Suripatty singled out education, pointing to people’s desire to learn alongside their appetite for entertainment.
The panel also challenged the terminology behind the session itself.
Dijksman suggested that “mobile content” still carries the legacy of ringtones and individual downloadable products. The expectation now is an ongoing service: a useful solution, a challenging game or an engaging drama.
“People don’t want that nowadays. They want a solution to a problem,” he said, discussing the limitations of older utility propositions.
Roy broadened the point to the experience across devices. Customers increasingly expect to move between a phone and a television without losing their place, with the presentation adapting to the screen.
For merchants, that raises the standard of the product being acquired. The service needs to justify a continuing relationship, as well as provide something that can be promoted successfully in an advertisement.
Advertising becomes experience
Suripatty’s presentation offered a practical way to close the gap between the advertisement and that experience: let people try something before asking them to subscribe. He demonstrated playable advertisements, where users interact with a small game experience before reaching the landing page. He also showed interactive end cards through which a video-service prospect could browse part of a catalogue and select something of interest.
The purpose is to build understanding and interest before the subscription request. Moving directly from a banner into “subscribe now” can leave too much unexplained.
“Let users discover, experience, or interact with content before subscribing,” he said.
Smadex can create these formats from clients’ creative assets, although merchants can also develop them themselves. The commercial case needs testing against the resulting customers’ value; the panel did not present a universal conversion or retention uplift.
This connects directly with the subscription session, where Overdrive Digital’s Kilian Espana described the advertisement as onboarding. A preview can make that idea tangible: customers learn what the product is before committing, giving the merchant a better chance of matching the acquisition promise to the actual service.
It also gives the cheap-traffic debate another dimension. An extra interaction before subscription may be worthwhile if it produces customers who understand the proposition and stay. Judging the creative solely by its immediate acquisition cost would miss that possibility.
AI could extend this approach into more personal discovery. Sam Media’s Dijksman described a shift towards customers expressing their needs in a dialogue, alongside conventional navigation. Instead of working through menus and categories, a user could explain what they want and receive a relevant response. The information in that conversation could help providers understand demand, choose content to license and identify gaps in their offering.
He also envisaged conversational discovery moving into the advertisement itself: a prospect describes a film, the service confirms it has something suitable, shows a trailer and then offers the subscription.
That was a possible next step, rather than a demonstrated replacement for the playable formats shown. Its appeal is that acquisition and product discovery become parts of the same interaction.
AI behind the scenes
Roy concentrated on what AI can change behind the service. Translation, lip-synchronised dubbing, editing and adaptation from horizontal to vertical video could make it quicker to prepare material for different audiences.
Balfort saw similar potential for licensed esports videos available in English that need adapting for other language markets. The opportunity is to make an existing product more relevant without reproducing the entire localisation process from scratch.
Roy’s emphasis was on building workflows around the business, rather than assuming that paying for more AI usage automatically produces efficiency.
“You use the tech to create more, create better, create fast,” he said.
He also described a discussion about personalised basketball clips, where a subscriber could request material featuring a preferred player and a system could assemble it from the available feed. The example illustrated a possible premium experience; it was not presented as an established commercial service with performance results.
The distinction is useful. Producing more content is one benefit, but giving somebody a reason to value the subscription more is the larger opportunity.
Yet the panel did not equate increased usage with a simple answer to retention. Roy argued that occasional consumption is normal in subscription businesses, while also acknowledging the difficulty of attracting attention amid notification overload.
Dijksman’s answer was to make the service more responsive to what people want. Suripatty framed the customer’s requirement as entertainment or value.
This extends the earlier subscription discussion: engagement should help explain the relationship, alongside billing, cancellations and purchase awareness. A service that customers actively seek out has a stronger proposition, but usage needs interpreting in context.
Payment has a key role
Payment choice was equally central to the product discussion. Dijksman argued that familiar payment methods improve the journey and that preferences differ sharply between markets. He also questioned the assumption that frictionless payment remains exclusive to DCB, while recognising the expertise telemedia businesses have built in carrier relationships and integrations.
Balfort used CFM’s NBA League Pass activity to illustrate complementary distribution. In certain markets, CFM offers access through DCB, while customers may also buy directly through other payment methods. Mobile money, she added, is too important in Africa to ignore.
Roy described orchestration as presenting a suitable set of choices for each market. His examples ranged from card-linked wallets to India’s UPI and Brazil’s Pix, with ease of use and trust shaping the customer’s willingness to transact. “The DCB business single biggest value is I trust my telco,” he said.
That emphasis sits alongside the header-enrichment session’s work on rebuilding secure, convenient identification. The customer-facing benefit must survive changes in the technology beneath it.
Data costs also influence what can be sold. Roy contrasted video-rich consumption in cheap-data environments with markets where data and phone storage are precious resources.
Bundling connectivity with content can therefore change the value proposition. Dijksman described African bundles as strongly operator-led, reflecting both consumer behaviour and carriers’ interest in selling data.
The Africa panel explored the economics in greater detail, including lower content revenue shares and activation difficulties. Together, the sessions show why a bundle must be assessed as a distinct distribution model, with its own costs and customer journey.
Direction of travel
Looking further ahead, Roy envisaged content carrying more commerce opportunities: viewers identifying products in a scene and moving towards a purchase. He expected subscriptions, advertising and commerce to become overlapping revenue sources.
The discussion explored that direction without presenting a deployed autonomous shopping journey. Its relevance is the possibility that a content audience could generate value through several forms of transaction.
For 2027, the panel offered signals rather than a definitive market map. Suripatty expected further opportunity in Kenya and Nigeria and favoured education. Balfort pointed to video and esports. Dijksman emphasised changing market conditions and the difficulty of naming a permanent winner.
The common requirement is adaptability: identify where commercial conditions support growth, show customers what the service offers, make it relevant and let them pay with confidence.
Telemedia’s next movers and shakers will need more than a hot category. They will need a service whose acquisition, experience and commercial model work together.
|Watch the full session here |


