


TL;DR
- Growth needs local knowledge: Smadex reports African ad spend on its platform rising almost 80% year on year, but language, content demand, taxation and acquisition channels vary sharply between markets.
- Payments and distribution are changing: Mobile wallets and data bundles offer new routes as merchants struggle with low airtime billing rates, with different economics from standalone DCB.
- Relevant content must be easy to use: Gaming, short dramas and local entertainment offer opportunities, but activation, affordability and coordinated customer support determine lasting value.
| Watch the full session here |
Africa’s mobile content opportunity is growing, but the model for capturing it is changing. A merchant can have traffic, demand and a working carrier-billing connection, yet still struggle to collect revenue because customers are keeping their money somewhere else.
That was one of the clearest messages from Telemedia Marbella’s Africa session. Mobile wallets, communication bundles and changing spending habits are reshaping how services are bought. For merchants and aggregators, the opportunity increasingly depends on reaching customers through the payment and distribution channels they actually use.
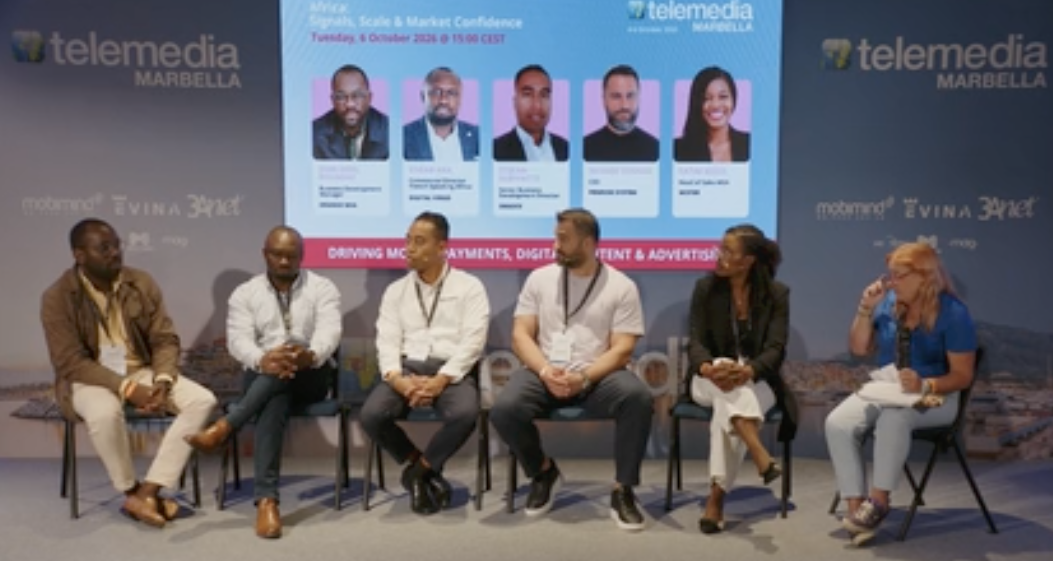
The panel, chaired by Louise Ford, brought together Stefan Suripatty, Senior business development director at Smadex; Jean-Noel Kouadio, Business development manager at Orange; Edgar Kra, Head of sales Africa at Digital Virgo; Fatim Keita, Head of sales EMEA at Wister; and George Togkas, CEO of Penrose Systems.
Suripatty opened with a striking indicator of activity. African advertising expenditure on Smadex’s platform had grown almost 80% compared with the previous year. “It’s almost doubled in terms of ad spend,” he said.
He highlighted Morocco and Tunisia, alongside Ghana, Nigeria and Kenya, with growth also appearing in markets including Angola, Botswana and Zambia. South Africa remained important, although he described it as relatively saturated.
That is a view of spending through Smadex, rather than a measurement of the entire African advertising market. Even so, it points to merchants committing more money across a widening range of countries.
| Watch the full session here |
Africa is many markets
The harder question is what that investment earns. Orange’s Kouadio cautioned against treating Africa as one market. Even broad distinctions between North Africa and sub-Saharan Africa leave significant differences in smartphone penetration, mobile-money adoption, regulation and consumer behaviour. “I think we need to address any market individually,” he said.
Digital Virgo’s Kra added taxation to that list. Payout structures and tax treatment can change the merchant’s actual return and headline country figures do not always reveal those differences. Kouadio said Orange’s partnership work involves consulting the group’s tax specialists before addressing markets.
Togkas from Penrose Systems similarly distinguished western, eastern, southern and central African conditions. Access to customers depends on the acquisition channels available, as well as demand for the product. A service that performs through web advertising in North Africa cannot simply be moved into a market where the relevant web audience is much smaller and operator channels remain important, he said.
Wister’s Keita added language and content preferences. French, English and Arabic are only the beginning of localisation; the discussion also pointed to the importance of local languages and cultural habits.
Her example was a wellness service welcomed by European operators, where it attracted favourable commercial terms, but which failed in Africa. “Premium service in Europe can be different in Africa,” she said.
The label does not establish demand. Short dramas, local entertainment and gaming may offer a stronger proposition than a product successfully sold elsewhere. Kouadio described gaming success in Morocco and Tunisia that could not simply be assumed in sub-Saharan markets. Keita highlighted the familiarity of short drama with audiences brought up on telenovelas. Togkas stressed that cloud gaming also depends on connectivity and latency: demand means little if the experience disappoints.
For operators, some of these services have an additional attraction. Video and gaming encourage data consumption, potentially adding value beyond the content payment itself.
The growing collection problem
But good content does not remove a growing collection problem. Kouadio explained that customers often commit spending to communication packages, leaving less money in their main airtime balance. Mobile wallets add another place where funds can sit.
For a merchant relying on standalone DCB, the result can be plenty of acquisitions but too few successful charges. Kra said Digital Virgo was seeing low main-balance billing rates continuing to decline over time. The response is to adapt distribution and payment flows with operators. The challenge, he explained, is finding customers through the payment methods they are now using.
That does not make DCB irrelevant. Kouadio argued for combining carrier billing and wallets, reflecting different behaviours across markets. He also noted that the mobile-money trend in sub-Saharan countries differs from that in much of North Africa.
Wallets bring their own friction. Kra described promising early work with wallet payment flows, while identifying automatic renewal as a further challenge to test.
Kouadio pointed to merchant onboarding and local-presence requirements as issues businesses must investigate in the markets they enter. He also described journeys that combine a digital interaction with a USSD step to obtain a verification code.
Those experiences show why adding a payment option is only part of the work. The journey must be suitable for purchasing digital content, while recurring billing, permissions and customer support need to work together.
There is also a change in how the customer regards the money being spent. Kra argued that wallet payments are treated more like spending cash or using a card, raising the stakes for purchase clarity and complaints.
Bundling boom
Alongside wallets, bundling offers a way to bring the content and the means to consume it into one purchase. Togkas described a South African gaming proposition built with an operator using its understanding of network usage. The bundle combines the merchant’s gaming service with data allocated to its use.
The customer buys access and connectivity together. The operator markets the offer through its own channels, allowing the merchant to discount the service without carrying the same external acquisition expense.
That trade-off matters. A lower service price or smaller revenue share can be commercially sensible when the cost of finding the customer changes.
Kouadio stressed that bundles operate on a different model from standalone DCB. They involve the operator teams responsible for mass-market data offers, whose priorities and economics differ from those of a conventional content partnership.
The content provider should not expect the familiar percentage of a standalone subscription. Kouadio suggested that even a very small share can be profitable where bundle volumes are sufficiently large.
That was an illustration of the potential economics, rather than a standard commercial offer. The calculation still depends on scale, rights costs, activation and what the provider must spend to deliver the service.
The operator, meanwhile, needs evidence that adding content creates incremental demand rather than simply redistributing revenue from a data package customers would already have bought.
Bundling can also fail at the point of use. Kra described a Moroccan offer containing data and several services, with payment linked to activation. Customers needed to understand the services and take the steps to activate them.
“It’s not working right now,” he said, explaining that the team was trying to improve the journey.
Kouadio argued that activation demonstrates real interest in the content. Kra’s concern was that the flow itself made activation difficult. Both points matter: inclusion in a bundle is no substitute for a proposition customers understand and can readily access.
Micro-pricing looks attractive
Micro-pricing offers another way to match products to spending habits. Kouadio described customers accustomed to buying and renewing data in small amounts, often daily. Asking for a large entertainment payment can therefore create a barrier.
Togkas described implementations where a customer paying a quarter of the daily price receives a corresponding period of access, such as six hours. Further charging depends on the operator integration and applicable rules.
The opportunity is flexibility, provided the customer understands the price and entitlement. Premium content still has to cover its costs, and retention depends on whether people want to return. “For the retention of any user, you need to have a relevant service,” Kouadio said.
Customer support becoming vital
Keita brought the discussion back to what happens after purchase. Customer support needs cooperation between the merchant, aggregator and operator – particularly where complaints surface through Facebook communities rather than formal review platforms.
Operators receive the complaints, but merchants know their services and may be better placed to resolve access problems or explain a purchase. Counting complaints without coordinating the response leaves that knowledge unused.
She described Wister approaching renewed opportunities in West Africa with greater emphasis on a regulated market and cooperation across the ecosystem. Togkas called for rules that protect customers while allowing business to operate, with enough stability for companies to invest.
The panel’s optimism was therefore practical. Growth exists, operators want relevant content and new payment routes are opening. But each opportunity requires its own commercial assessment.
Kra’s closing advice was to visit the countries and observe how people consume services and use data. Togkas added: “Find the best local partner.”
Africa’s next phase of mobile content growth will be built around those habits. The winning proposition may be a standalone subscription, a wallet purchase, a few hours of access or a service tied to data. Merchants need to establish which combination customers understand, can afford and want to keep using – and then run the numbers accordingly.
| Watch the full session here |


